The program lists no prior auto credit history and no adverse credit history, at least six months of verifiable current full-time employment, a down payment of $750 or more and a minimum 620 FICO score. Additional documentation may be required, and a co-signer or higher down payment may be required based on credit history and underwriting guidelines.
That combination creates a communication challenge. A first-time buyer may not know how APR, down payment, term, insurance, maintenance and total cost of ownership fit together. A dealer may have the right vehicles and financing path but still lose momentum if the customer arrives unprepared or if sales, BDC and finance teams explain the program differently.
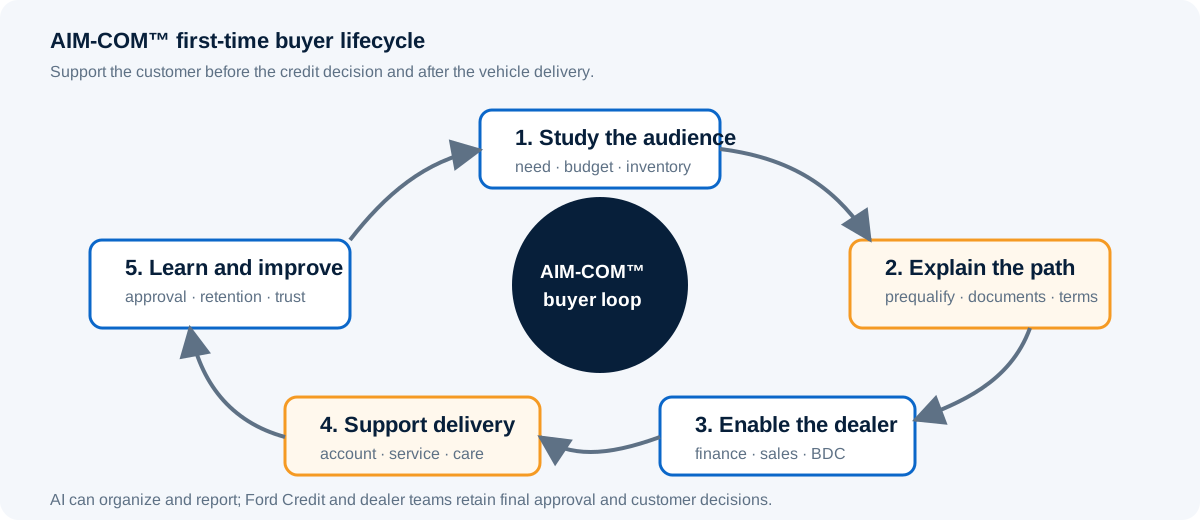
AIM-COM™ can frame the program as an operating system for customer enablement: study the audience, explain the eligibility path, secure the documents, coordinate dealer teams, track service levels and learn from approvals, declines, drop-offs and post-purchase behavior.
For a first-time buyer, clarity is not a soft benefit. It is part of the conversion path and the customer experience.
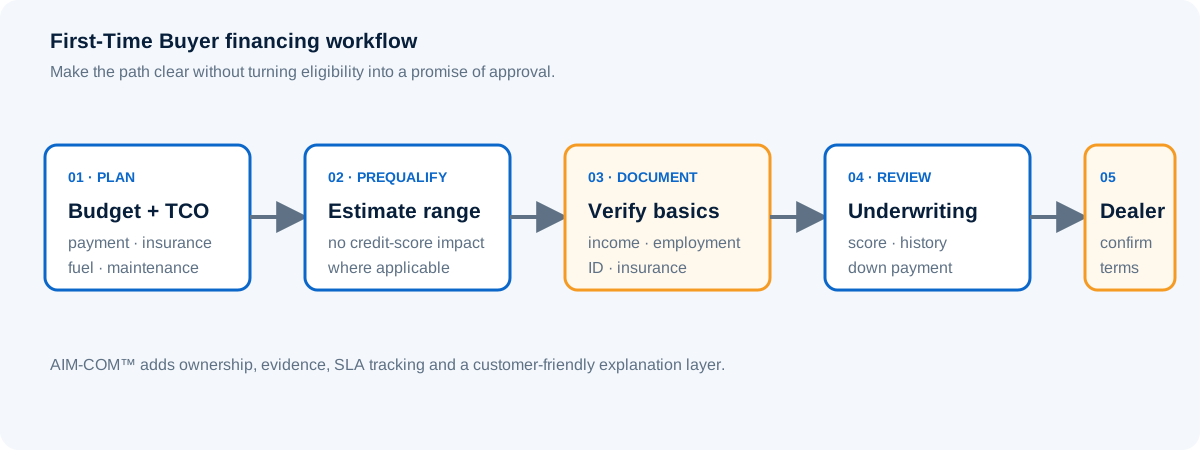
What the Ford First-Time Buyer Program Describes
The official Ford Credit page presents the program for people financing their first vehicle, including applicants with limited credit history. It says eligible customers may choose new and Certified Pre-Owned Ford vehicles, and qualified applicants may be eligible for a lower APR.
The page also describes $750 Bonus Cash on new Ford vehicles, subject to Ford Credit financing and qualification; financing up to $50,000; terms up to 84 months; and low down payment options. These are program descriptions, not individualized approvals.
| Program area | Reported detail | Operating control |
|---|---|---|
| Vehicle choice | New and Certified Pre-Owned Ford vehicles are described as options. | Match customer needs, inventory, warranty and total cost of ownership. |
| Potential incentive | $750 Bonus Cash on new Ford vehicles with Ford Credit financing, subject to qualification. | Confirm active program, offer combination and customer qualification. |
| Financing amount | Financing up to $50,000 is described on the page. | Separate advertised range from final underwriting decision. |
| Term | Flexible terms up to 84 months are described. | Explain payment, total interest and long-term ownership implications. |
| Credit history | No prior auto credit history and no adverse credit history are listed. | Use careful language and avoid informal approval promises. |
| Employment | At least six months of verifiable current full-time employment is listed. | Define acceptable evidence and secure submission. |
| Down payment | $750 or more is listed; higher down payment or co-signer may be required. | Present alternatives without pressuring the customer. |
| Credit score | Minimum 620 FICO score is listed. | Verify current criteria and keep final underwriting ownership clear. |
Conservative qualification
Prequalification is not final approval. The official page says not all buyers qualify, and final terms may depend on credit history, documentation, underwriting guidelines, vehicle, dealer and current program rules.
Why First-Time Buyers Need a Different Dealer Workflow
A first-time buyer often needs more education than a repeat buyer. The customer may be comparing monthly payment rather than total cost, may not know which documents are needed, or may be uncertain about the difference between a prequalification estimate and a firm credit decision.
AIM-COM™ could help the dealer design one consistent explanation across marketing, BDC, sales and finance. The workflow should answer five basic customer questions: What can I realistically afford? What may I qualify for? What documents do I need? What happens when I visit the dealer? What support will I receive after delivery?
1. Study the Audience and the Local Market
The first step is not to advertise the incentive everywhere. It is to understand the audience around each dealer. The study could include first-time buyer age ranges, employment patterns, local income context, college or workforce communities, new versus Certified Pre-Owned demand, insurance costs, inventory, payment sensitivity and competitor financing messages.
This does not require the dealer to infer sensitive personal characteristics. It requires a responsible market baseline and clear consent where customer-level data is used. The output should identify where education, prequalification and dealer support are likely to be most useful.
| Market question | Possible signal | Decision supported |
|---|---|---|
| Who is the audience? | First-time buyers, limited credit history, new workforce or college segments. | Message, channel and educational content. |
| What can they afford? | Payment ranges, insurance, fuel or charging and maintenance context. | Vehicle mix and payment-calculator experience. |
| What inventory fits? | New and Certified Pre-Owned Ford availability by model and price. | Landing page, lead routing and dealer appointment path. |
| Where does friction occur? | Drop-off before prequalification, missing documents or unclear terms. | Content, training and SLA improvement. |
2. Explain Eligibility Without Overpromising
Program language should be specific enough to help customers prepare and cautious enough to avoid implying approval. The message can state the criteria shown by Ford Credit, then direct customers to prequalification and the local dealer for confirmation.
| Customer question | Clear explanation | Control needed |
|---|---|---|
| Do I need prior auto credit? | The program is intended for first-time buyers and lists no prior auto credit history. | Do not equate “no prior history” with automatic approval. |
| What employment evidence may be needed? | The page lists six months of verifiable current full-time employment. | Confirm acceptable documentation with authorized finance teams. |
| How much should I put down? | $750 or more is listed, but a higher amount or co-signer may be required. | Explain that the final requirement can vary. |
| Is the $750 Bonus Cash guaranteed? | It requires Ford Credit financing and not all buyers qualify. | Confirm current program terms before quoting the offer. |
| Is prequalification approval? | No. It is an estimate that can help frame the shopping range. | Keep underwriting decision ownership with Ford Credit. |
3. Make Documentation Secure and Predictable
The official page suggests preparing a driver’s license, proof of insurance, proof of income and financing or trade-in information. AIM-COM™ could turn this into a secure document checklist with status, ownership, submission date, reviewer and clarification reason.
Document workflows should avoid unnecessary copies in email or personal messaging. Access should be role-based, the retention period should be defined and the audit trail should show who reviewed what. AI may classify missing fields or summarize a queue, but it should not make a credit decision.
| Evidence | Purpose | Control |
|---|---|---|
| Driver’s license | Identity and customer record match. | Secure upload and limited access. |
| Proof of insurance | Preparation for the vehicle transaction. | Confirm current requirement and document status. |
| Proof of income | Supports employment and income verification. | Authorized review, redaction and retention controls. |
| Employment history | Supports the listed six-month current full-time employment condition. | Record source and clarification requests. |
| Trade-in information | Supports valuation and transaction planning where applicable. | Separate trade value from credit eligibility. |
4. Set SLAs for Prequalification, Clarification and Dealer Handoffs
First-time buyers can lose confidence when a lead waits without an update. AIM-COM™ could help define SLAs for responding to a prequalification inquiry, acknowledging documents, requesting clarification, routing an appointment and confirming the next owner.
| Stage | Example SLA definition | Measure |
|---|---|---|
| Lead intake | Confirm receipt and explain the next step. | Time to acknowledgment and contact rate. |
| Prequalification | Provide a clear estimate path without promising approval. | Completion rate and drop-off point. |
| Document review | Identify missing or inconsistent information. | First-pass completeness and clarification cycles. |
| Dealer handoff | Route the customer to a trained sales or finance owner. | Appointment rate and handoff time. |
| Final decision | Keep underwriting decision with authorized Ford Credit and dealer finance teams. | Decision time and exception age. |
| Post-purchase support | Explain account management, payment and service support. | Activation, questions and early customer experience. |
How AIM-COM™ Could Improve Dealer Execution
AIM-COM™ is most useful when it connects the customer promise to the work performed by each team. A first-time buyer program can be promoted by marketing, qualified by Ford Credit, explained by sales, documented by finance and supported after delivery. Without shared ownership, the customer may receive five different versions of the process.
| AIM-COM™ layer | First-Time Buyer application | Output |
|---|---|---|
| Strategy & Outcomes | Define whether the goal is qualified leads, financed deliveries, customer education, credit confidence or dealer retention. | Baseline and measurable objectives. |
| Co-op Economics | Separate bonus cash, media investment, dealer effort, finance operations and post-purchase support. | Visibility into program cost and value. |
| Governance & Risk | Control claims, criteria, documents, access, privacy, approvals and exceptions. | Consistent and auditable execution. |
| Network Enablement | Train BDC, sales and finance teams on one customer-friendly explanation. | Fewer conflicting messages and preventable drop-offs. |
| Activation & Operations | Coordinate landing pages, prequalification, appointments, documents and delivery support. | Visible handoffs and SLA performance. |
| Intelligence & Improvement | Analyze eligibility questions, document gaps, approvals, declines, drop-offs and post-purchase support. | Evidence for the next program and dealer playbook. |
AI-Assisted Reporting With Human Accountability
AI could analyze program activity by state, region, dealer, model, new versus Certified Pre-Owned, lead source, document stage and time period. It could summarize where customers ask the same question, which dealers have slow handoffs, which documents create the most clarification and where prequalification activity does not translate into appointments.
Illustrative AI prompt
“Analyze First-Time Buyer campaign activity by dealer and stage. Identify the largest drop-off between inquiry, prequalification, document completion, appointment and delivery. Summarize recurring customer questions and document gaps. Do not infer creditworthiness or make approval decisions. Recommend process improvements for human review.”
Use de-identified or appropriately protected data, role-based access, approved prompts, audit logs and a clear owner for every recommendation.
Measure Goals, Gaps and Customer Trust
| Objective | Possible measure | Learning question |
|---|---|---|
| Audience reach | Qualified traffic, education content engagement and prequalification starts. | Did the message reach customers who needed the program? |
| Process completion | Prequalification completion, document completeness and appointment rate. | Where did customers lose momentum? |
| Dealer execution | Response time, handoff quality, clarification cycles and SLA performance. | Which dealer workflow needs support? |
| Commercial outcome | Financed deliveries, model mix, bonus-cash usage and cost context. | What happened beyond the number of leads? |
| Customer experience | Questions, complaints, clarity feedback and early account support. | Did the program create confidence or confusion? |
| Unmet objectives | Low regions, weak segments, declines and unanswered questions. | What should change rather than be explained away? |
Dealer Research and Post-Purchase Learning
Research should include BDC, sales, finance, managers and customer-support teams. Ask whether the program was easy to explain, whether criteria were clear, whether the document path felt secure, whether the customer understood the payment and total cost, and whether post-purchase support was connected to the original promise.
The learning record should preserve recurring questions, missing-document reasons, SLA performance, approval and decline patterns, dealer differences, customer feedback and the process changes that improved or weakened completion. This gives the next campaign a practical starting point.
The Bottom Line
The Ford First-Time Buyer Program addresses a real customer barrier: the uncertainty of financing a first vehicle with limited or no prior auto credit history. Its stated criteria and offers may be useful, but the customer experience depends on how clearly the program is explained and how consistently the dealer executes the handoffs.
AIM-COM™ could support the full operating path—from market study and eligibility communication to secure documents, dealer SLAs, AI-assisted reporting and post-purchase learning. It would not replace Ford Credit underwriting or promise approval. It would make the process easier to govern, explain and improve.
A financing program earns trust when the customer understands both the opportunity and the conditions attached to it.
Frequently Asked Questions
What does the Ford First-Time Buyer Program offer?
The official Ford Credit page describes financing support for first-time buyers, including limited credit history, possible lower APR for qualified applicants, $750 Bonus Cash on new Ford vehicles when using Ford Credit, financing up to $50,000 and terms up to 84 months, subject to qualification and current terms.
What eligibility criteria are listed?
The page lists no prior auto credit history and no adverse credit history, at least six months of verifiable current full-time employment, a down payment of $750 or more and a minimum 620 FICO score. A co-signer or higher down payment may be required.
Does prequalification guarantee approval?
No. Prequalification is an estimate and final approval remains subject to Ford Credit underwriting, documentation, vehicle, dealer and other applicable requirements.
How could AIM-COM™ support the program?
AIM-COM™ could organize audience study, eligibility communication, secure documentation, dealer enablement, SLA tracking, AI-assisted reporting and post-purchase learning while leaving credit decisions to authorized human teams.
Reference
Ford Credit First-Time Buyer Program. Offers, underwriting criteria, documentation and dealer requirements should be reconfirmed before publication or campaign execution.
Make first-time buyer programs easier to understand and improve.
AIM-COM™ helps OEMs and dealer networks connect customer education, financing eligibility, secure documents, dealer enablement, AI reporting and measurable outcomes.
Explore the AIM-COM™ Approach